Small ranges, and the band-to-band longs paid
With most names holding tight intraday ranges, our desk traders worked lower-band entries against clear daily levels and took profit into VWAP rather than waiting for extension. One long was scaled out in thirds with the stop moved to breakeven after the first target, and another was framed on a tight risk under a double bottom and closed exactly where it was planned. A short and a second attempt in an earlier name were cut without argument.
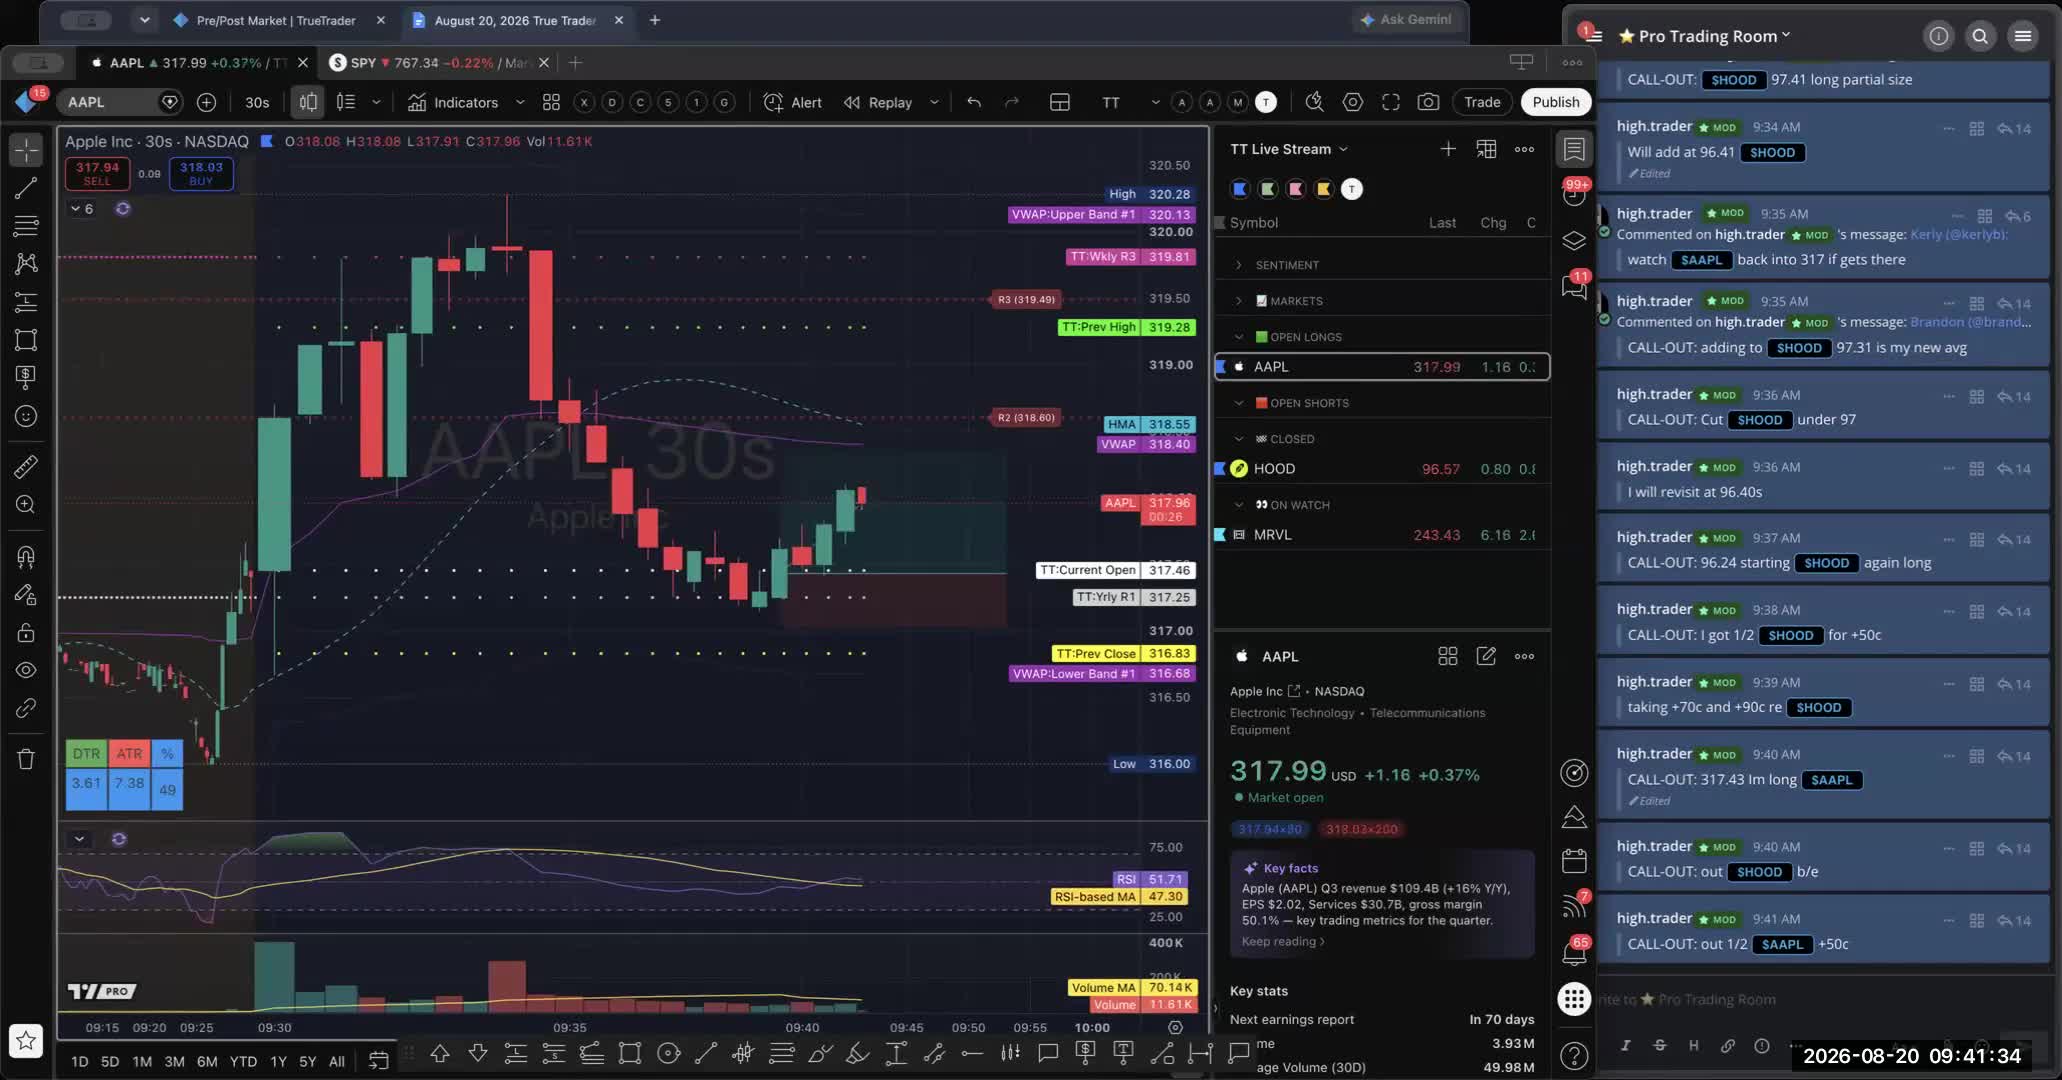
The 1h 11m session is on the other side of this.
Everything above is the write-up. This is the morning itself, with the names on every call and the room talking through it.
Robinhood set the tone early. A partial-size start on the cross, an add, then a quick cut and an immediate restart a little lower — the position was rebuilt to full size at a better average rather than defended at the first one. Half came off into the move, and when the bounce looked weak the stop went to breakeven and the rest closed there. Not a big trade, but the mechanics were the point: start small, add on confirmation, and treat a breakeven exit as a decision rather than an escape.
Apple was the cleanest work of the session. The entry came off the lower band on the cross, scaled out in thirds as it moved, with the stop lifted to breakeven after the first partial and the last piece taken into VWAP because the target was sitting right there. Rocket Lab was structured the same way from the other side of the desk — a double bottom over a quarterly pivot and a 20-day, risk defined under the lows at roughly thirty cents, target just beneath VWAP where the name had broken down earlier. It went almost straight there and was closed at the plan.
Two trades did not work. An Uber short taken band-to-band was stopped over the high base with no slippage and no hesitation, and a second Robinhood long later in the morning gave back a little. Both were sized as attempts, not convictions. The thread running through the last half hour was a point made aloud on the desk: when the ranges are this tight it's easy to get complacent about size, and the adjustment needs to happen before volatility widens out again, not after.
The morning in figures
Net points are per share. Apply your own size to get your own number: at 1,000 shares, 0.68 points is $680.00. At 100 shares it is $68.00. At one share it is $0.68. The desk publishes the move, not a dollar result, because the dollars depend entirely on how you size, and that is your decision rather than ours.
Every trade called that morning
Losers included. Rows with more than one leg were scaled out; open any row to see each exit.