A flat tape where only the scaled entries paid
Markets opened flat ahead of a heavy earnings week, and the desk worked small starters off short-timeframe confirmation rather than chasing the open. One index-name long got room to work and was taken off in thirds; a breakdown attempt was cut under the lows, another position scaled into a break-even stop, and a starter that was still being averaged got flushed by two large red candles. Mixed morning that finished slightly red.
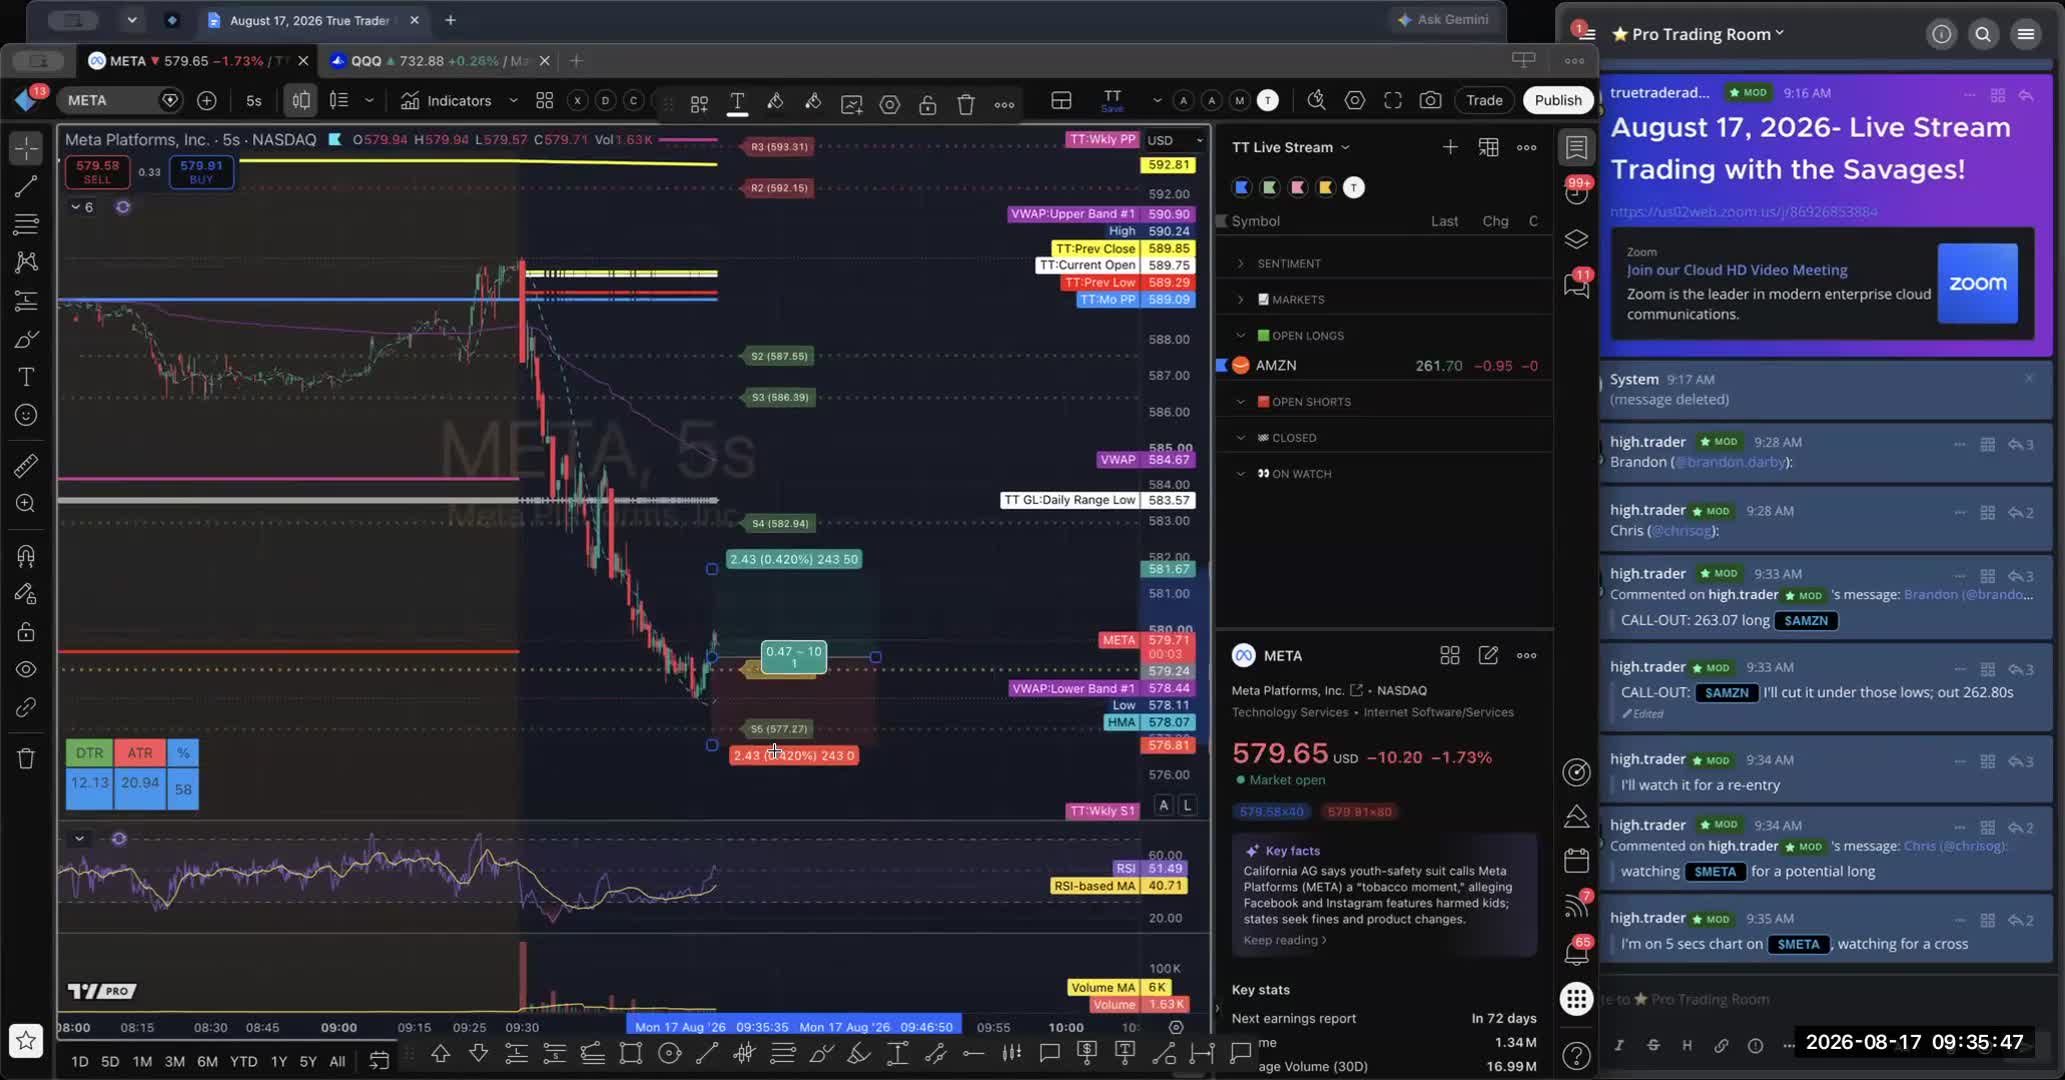
The 1h 10m session is on the other side of this.
Everything above is the write-up. This is the morning itself, with the names on every call and the room talking through it.
The best-managed trade of the morning was the META long. It was started small on a five-second cross, with the plan stated out loud before entry — one add if it came back down, stop under the low just made. It never came back, so the add never happened, and the position came off in thirds as it extended. Nothing was held for a hero exit; the last piece was let go when the move started to hesitate rather than after it turned.
Two attempts ran into a broker problem that had to be traded around rather than traded through. Orders were taking twenty-plus seconds to fill or silently cancelling, which changed the decisions: the AMZN long was cut under the lows and the intended re-entry was abandoned, and the ORCL long was scaled in pieces because the intended size-down would not execute, then stopped out at break-even on the retest. Declaring 'this is my last trade' while the platform was unreliable was the right call, even though it meant standing down on setups that later looked clean.
The DELL long is where the cost was. It was a starter with the stop under the lows, the add would not fill in a thin, spready tape, and by the time the add did go through the new average was barely better than the first entry — then two big red candles took it out. Averaging into a thin name to improve a price is the part worth reviewing: the fill problem was information about liquidity, not just an inconvenience. After 10:30 nobody forced anything else, which is why a single bad flush was the extent of the damage.
The morning in figures
Net points are per share. Apply your own size to get your own number: at 1,000 shares, 0.23 points is −$230.00. At 100 shares it is −$23.00. At one share it is −$0.23. The desk publishes the move, not a dollar result, because the dollars depend entirely on how you size, and that is your decision rather than ours.
Every trade called that morning
Losers included. Rows with more than one leg were scaled out; open any row to see each exit.